
New tax rules taking effect October 1 will bring certain overseas suppliers of Maldivian tourism products and related booking services into the country’s GST regime
The Outbound Tour Operators Association of India (OTOAI) has urged the Maldivian Government to reconsider the extension of the country’s 17% Tourism Goods and Services Tax (TGST) to certain overseas businesses involved in selling Maldivian tourism products.
The association’s appeal comes ahead of October 1, 2026, when amendments to the Maldives Goods and Services Tax Act take effect. Under the changes, the supply of inbound tourism products in the Maldives, together with related agency and booking services provided by businesses without a fixed place of business in the country, will be brought within the GST framework.
The change has implications for international travel companies and intermediaries selling Maldives holidays from overseas markets, including India.
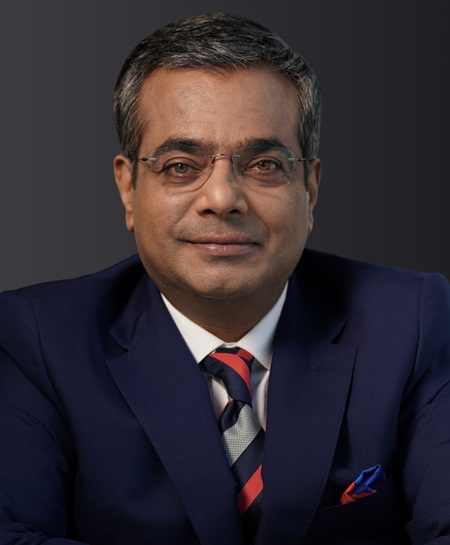
Himanshu Patil, President of OTOAI,
Overseas tourism suppliers to enter GST framework
The Maldives Inland Revenue Authority (MIRA) issued a circular on September 11 setting out registration requirements for affected suppliers.
MIRA defines an inbound tourism product as accommodation, meals, transport or any other tourist activity in the Maldives. Under the amended legislation, overseas suppliers of such products, as well as businesses providing related booking or agency services, are required to register under the tourism sector of the GST system if they do not maintain a fixed place of business in the Maldives.
The tourism-sector GST rate is currently 17%, following an increase from 16% that came into effect on July 1, 2025.
The new provision therefore does not represent a new increase in the TGST rate itself. Rather, it expands the scope of transactions subject to the 17% tourism-sector rate from October 1.
OTOAI raises concerns over impact on Indian travel trade
OTOAI has expressed concern that the additional tax and associated compliance requirements could affect the economics of selling Maldives holidays in overseas markets.
The association said Indian travel companies have played an important role in developing the Maldives as an outbound destination and argued that the new provisions could place additional pressure on travel businesses and consumers.
Himanshu Patil, President of OTOAI, said the association recognised the importance of tourism revenues to the Maldives but believed the new taxation framework could affect the destination’s competitiveness.
“We fully understand the importance of tourism revenues for the Maldives. However, at a time when the global travel industry is facing significant challenges, we believe an additional 17 per cent tax on overseas travel trade could unintentionally make the Maldives less competitive,” Patil said, according to the statement supplied by OTOAI.
He called on the Maldivian Government to reconsider the provision and continue discussions with international travel trade representatives.
Implications for advance bookings
One of the issues raised by OTOAI concerns holidays that have already been contracted and sold.
Maldives holidays are frequently booked well in advance, with tour operators and travel companies agreeing prices with customers before the date of travel. OTOAI said the introduction of an additional tax liability could create questions around existing contracts, margins and the final price paid by travellers.
However, the Maldivian GST regulations contain specific provisions concerning transactions involving affected overseas suppliers.
MIRA’s consolidated GST Regulation states that GST is not chargeable on certain supplies covered by the new provision if a tax invoice, invoice or receipt was issued before October 1, 2026, or full or partial payment was made before that date.
This provision is particularly relevant to travel companies handling bookings made and paid for before the new rules come into force.
Registration and compliance requirements
The new framework also introduces specific registration procedures for overseas suppliers.
MIRA’s regulations provide for a dedicated GST Registration – Overseas Suppliers process for businesses without a fixed place of business in the Maldives that carry out taxable activities.
For suppliers covered by the new inbound-tourism provision, GST return filing and payment requirements also take effect from October 1, 2026.
The changes therefore have implications beyond the tax amount itself, potentially requiring affected overseas travel businesses to review their accounting, invoicing and booking systems and their contractual arrangements with Maldivian suppliers.
Maldives already applies a 17% tourism-sector GST
The Maldives has operated a separate GST structure for tourism and general sectors.
MIRA currently lists the tourism-sector rate at 17%, compared with 8% for the general sector. The tourism category includes establishments such as resorts, hotels, tourist guesthouses, tourist vessels, spas and other tourism-related businesses, as well as travel agency service providers.
The 17% tourism rate has been in force since July 1, 2025.
The October 2026 change consequently extends the tax framework to a specific category of overseas suppliers of inbound tourism products and related agency or booking services, rather than raising the existing TGST rate.
OTOAI seeks wider industry consultation
OTOAI has called for further consultation between the Maldivian Government, international travel trade associations and Maldivian tourism industry organisations before measures affecting overseas distribution partners are implemented.
The association said it wanted to work with Maldivian tourism stakeholders to identify an approach that protects government revenue while maintaining the destination’s competitiveness in international markets.
The issue is particularly relevant to markets such as India, where tour operators and travel agencies play an important role in distributing resort accommodation, packages and other tourism products.
Potential impact on Maldives travel distribution
The new rules come as international travel businesses increasingly sell destinations through digital platforms and cross-border distribution networks. The Maldives’ decision to bring certain overseas tourism-product suppliers and booking or agency services into its GST system represents a significant change in how cross-border tourism transactions are treated for tax purposes.
For travel companies, the immediate priority will be understanding whether their specific business model falls within the amended provisions and completing any required registration and compliance procedures.
For travellers, the ultimate impact will depend on how overseas suppliers incorporate the tax into package pricing, contracts and distribution arrangements.
OTOAI said it remained committed to the Maldives market and to working with the country’s tourism industry to maintain the long-standing India–Maldives tourism relationship.